The Reference For Knowing When Two Positions Are Secretly The Same Bet Twice
Two positions that move together aren't really two positions.
You'll get a one-page summary of the tendencies that show up across public trading education, things like the dollar and gold, stocks and bonds in a risk-off stretch, oil and energy names, worked onto a single page you can glance at before a trade goes on instead of after.
You'll get a second page built for writing down what you actually see over time, in your own words, with your own dates, so the sheet gets more useful to you specifically the longer you use it.
Most traders already know, in theory, that correlated positions aren't true diversification.
Fewer keep an actual reference of which common pairs have historically tended to move together, and which have tended to move opposite each other.
It isn't a live correlation calculator, and it isn't current data.
Correlation between any two instruments moves constantly and can weaken or flip without warning.
This is a starting reference, not a conclusion, built to be checked against current conditions, not substituted for them.
This is a starting reference, not a conclusion, built to be checked against current conditions, not substituted for them.Jason Parker, Founder of Trading Habits
Introducing The Asset Correlation Reference Sheet.
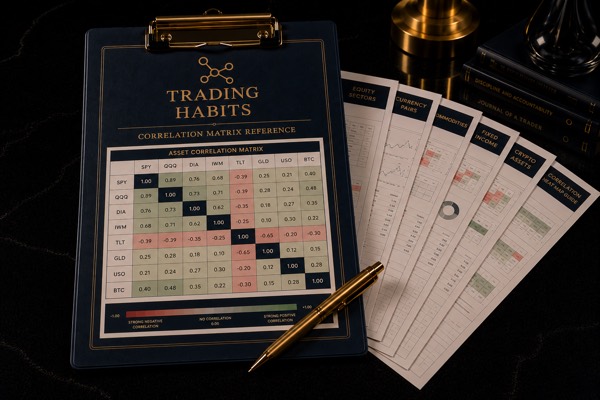
The Asset Correlation Reference Sheet
General tendencies between common asset pairs, and a page for what you actually observe.
- Format PDF, 6 pages, print or read on screen
- Covers General historical tendencies for common asset pairs
- Includes A blank correlation observations log for your own notes
- Delivery Instant download right after checkout
General reference only. Not current or live data.
What's Inside
What's Inside The Asset Correlation Reference Sheet
- 01A one-page summary of general tendencies commonly described in public trading and finance education, for pairs like USD and gold, stocks and bonds, and oil and energy stocks, so you have a starting check before a position goes on instead of a guess.
- 02Plain-English context on why correlation shifts, weakens, and sometimes reverses over time, so you stop treating a pairing as fixed right at the moment it matters most, under stress.
- 03A short explanation of why correlated positions behave more like one larger position than two independent ones, so you can catch when you're doubling risk while thinking you're diversifying.
- 04A blank "My Correlation Observations" log with columns for date, pair, and what you personally saw, so the sheet turns into your own evidence over time instead of staying a static reference.
- 05Clear framing throughout that every relationship on the sheet is a general tendency, not a live or guaranteed reading, so you're never fooled into treating an old pattern like current fact.
- 06Guidance on where to check an actual, current correlation figure if you need one for genuine decision-making, so this sheet points you to actual data instead of pretending to be it.
- 07A short "How To Use This Sheet" page up front, explaining what it does and doesn't do, so you're using it correctly from the first read instead of guessing at its limits.
- 08One printable sheet, no login, no app, no subscription, so it lives on your desk or in your trading binder and stays useful with no moving parts to break.
HABITS
★
Certificate of Guarantee
60-Day, No-Questions-Asked
If The Asset Correlation Reference Sheet doesn't earn a spot in your files, email us any time within 60 days of purchase for a full refund. No form to fill out. No reason required.
Instant Download
$6One-time payment. No subscription.
Order Now6-PAGE PDF · DELIVERED IMMEDIATELY AFTER CHECKOUT · 60-DAY GUARANTEE
Behind The Tool
Where The Idea Of Correlation Comes From
The Concept
Correlation measures how closely two things move together, on a scale from -1 (perfect opposite movement) to +1 (perfect same-direction movement), with 0 meaning no relationship at all. Applied to two positions, a correlation near +1 means they're likely to rise and fall together, so holding both isn't really diversification. It's the same bet twice.
None of that describes what a pairing did last week. Correlation between any two instruments is not fixed. It drifts with the macro backdrop, and it can weaken or flip entirely during stress, which is exactly when traders most need it to hold.
Where It Comes From
The statistical correlation coefficient traces back to Francis Galton's work on heredity in the 1880s, formalized mathematically soon after by his student Karl Pearson, whose name is still attached to the standard formula used across finance today, the Pearson correlation coefficient.
Its use in portfolio construction owes the most to Harry Markowitz's 1952 paper "Portfolio Selection," which showed mathematically that combining assets with low or negative correlation could reduce a portfolio's overall volatility without necessarily reducing its expected return. That paper became the foundation of Modern Portfolio Theory and won Markowitz a share of the 1990 Nobel Prize in Economics.
Two Illustrative Shapes: Together vs. Opposite
Illustrative shapes only, not live prices: two lines rising and falling together on the left, two lines mirroring each other on the right. Genuine correlation is rarely this clean, and it drifts. Check current conditions before assuming either pattern still holds.
Try It: Markowitz's Own Diversification Math
Two equally weighted positions, each with the volatility you enter, combined using Markowitz's own 1952 formula: portfolio volatility = volatility × √(0.5 × (1 + ρ)). Drag ρ toward -1 and combined risk shrinks toward zero. Drag it to +1 and diversification stops doing anything at all, since two perfectly correlated positions are, risk-wise, the same bet twice.
Background only. The sheet itself lists general tendencies and gives you a page to log what you actually observe.
Common Questions
Who came up with the correlation coefficient used on this sheet?
Francis Galton's work on heredity in the 1880s laid the groundwork, and his student Karl Pearson formalized the math soon after. The Pearson correlation coefficient is still the standard formula finance uses today.
Why does correlation matter for diversification?
Harry Markowitz's 1952 paper "Portfolio Selection" showed that combining assets with low or negative correlation can reduce a portfolio's overall volatility without giving up expected return. It became the foundation of Modern Portfolio Theory and won Markowitz a share of the 1990 Nobel Prize in Economics.
Is a correlation number fixed once you look it up?
No. Correlation between any two instruments drifts with the macro backdrop, and it can weaken or flip entirely during stress, exactly when a trader most needs it to hold. That's why the sheet leaves room to log what you actually observe instead of treating one number as permanent.