There is a date already sitting on your calendar right now that your current stop distance was never built for.
Not a surprise headline. Not a flash crash. A date you can look up this second: an earnings release, a Federal Reserve decision, a CPI print.
Your broker may already be telling you, in plain dollars, how much bigger that day is priced to be than an ordinary one.
Most positions never get resized for it anyway.
The stop stays where an ordinary day put it. The size stays where an ordinary day set it. The date arrives right on schedule.
Two academic mechanisms explain why a date you know perfectly well still gets treated like any other session, and neither one has anything to do with not paying attention.
You'll get the exact math connecting a scheduled release to a stop that can't fill at its own price, two worked accounts with actual dollar figures, and a 3,000-account simulation that changes exactly one sizing rule between two otherwise identical strategies.
Introducing The Catalyst Trade.
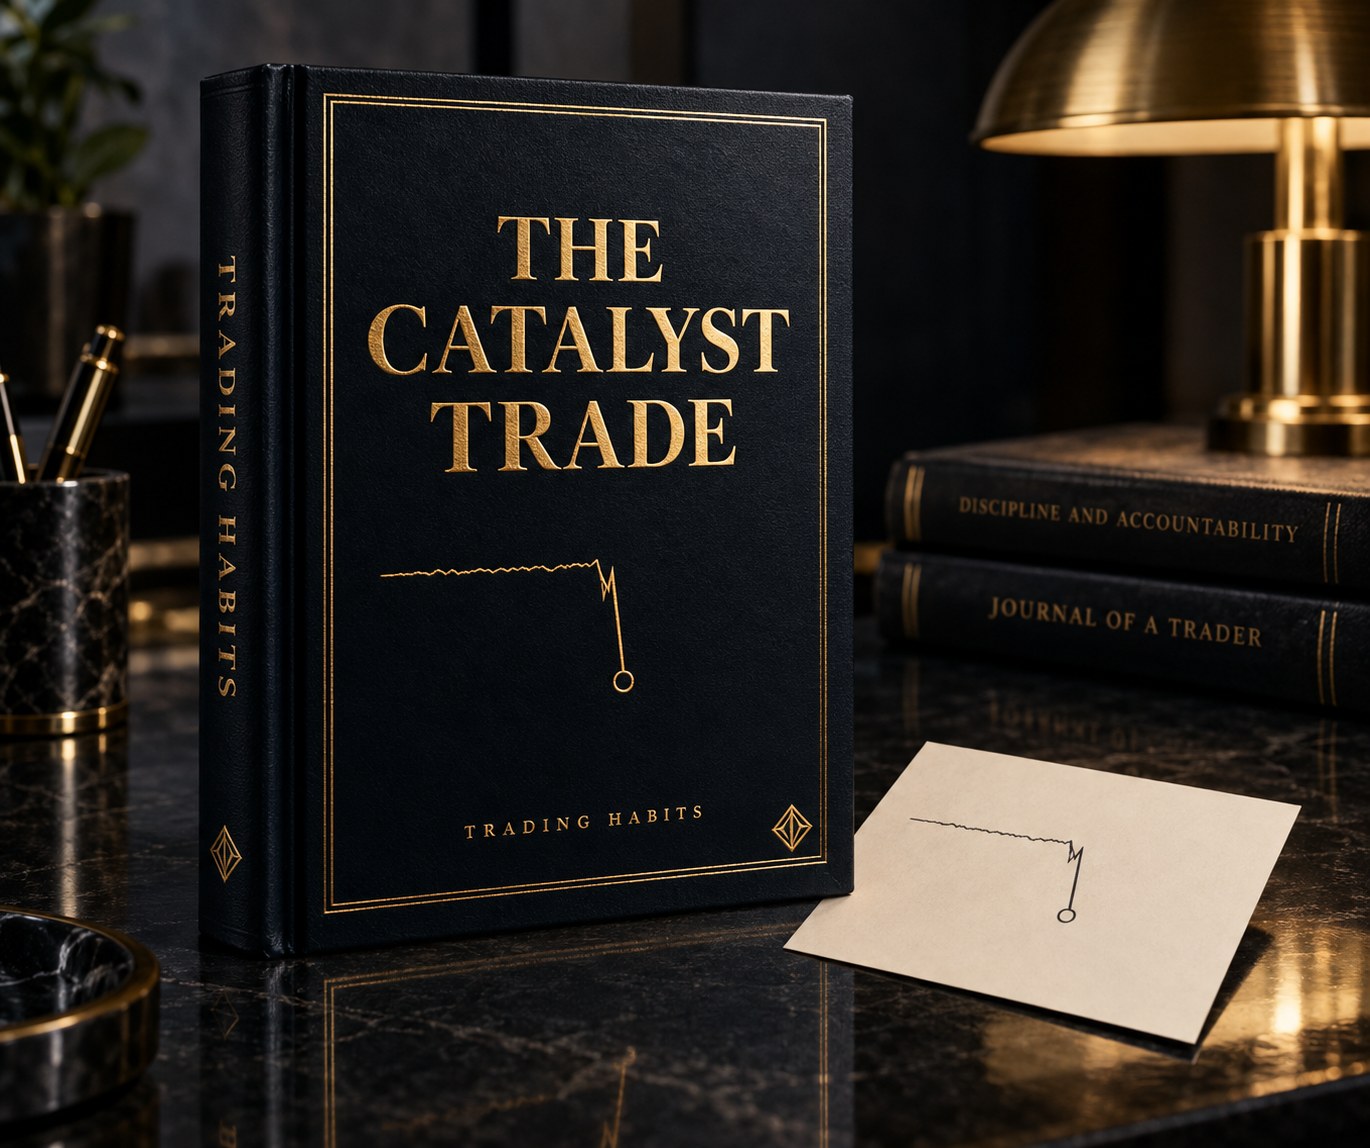
A Trading Habits Report
The Catalyst Trade
The position sized for an ordinary day, carried straight through a scheduled release, without ever being resized for what that day can do.
- Length 20 pages, with 7 original charts and two worked composite case studies
- Author TradingHabits.com
- Format PDF, delivered as an instant download right after checkout
- Covers The research behind why a known date still gets sized like an ordinary one, the math connecting a scheduled release to gap and liquidity risk, two worked case studies, and a 3,000-account Monte Carlo simulation comparing event-blind sizing against event-adjusted sizing
This report breaks down the research, the math, and the numbers on one specific decision.
What's Inside
20 Things This Report Actually Says
- 01The one difference between this report's subject and the failure covered by every other report in this shop, and why it involves more information, not less.Page 2
- 02Five terms this report defines once, including the exact line separating a position that adjusts for a known date from one that doesn't.Page 3
- 03The three instrument types this report says share the identical underlying mistake, despite trading nothing alike.Page 4
- 04The specific options-math figure already sitting on most broker platforms before an earnings release, and what it means when a stop distance ignores it.Page 5
- 05The 1979 study behind why options pricing already treats a scheduled release differently, weeks before the trade is ever opened.Page 5
- 06Two named psychological studies, a 1973 paper and a 1980 paper, that explain why a known date still gets sized like an ordinary one.Page 6
- 07The repeatable shape this report says the options market assigns to every scheduled release, and the one session where that shape peaks.Page 7
- 08The exact two-number formula this report uses to define a position's dollar risk, and the one thing a scheduled release changes about it without changing the stop distance at all.Page 8
- 09A $30,000 account, a stop set at entry, and the exact dollar loss produced by a single overnight gap, worked share by share.Page 9
- 10A $50,000 funded-evaluation account, an 8-point futures stop, and the specific point count the actual fill landed past where the stop was resting.Page 10
- 11Four psychological triggers, named individually, and the one thing a genuinely known date does to two of them that a surprise headline never could.Page 11
- 12Four sentences traders say to themselves in the days before a scheduled release, each one matched to the exact trigger producing it.Page 12
- 13The one position type this report names where gap risk and a second, separate liquidity risk stack directly on top of each other.Page 13
- 143,000 simulated accounts, 150 trading days, and one sizing rule changed on exactly one type of day.Page 14
- 15The exact modeled spread, in R, between the two simulated groups, and the specific percentile this report uses to show what a genuinely bad run looks like for each one.Page 15
- 16The full stated assumption behind this report's fat-tail event-day model, including the one rule that decides how much size actually gets cut.Page 16
- 17Four steps this report lays out for sizing a known date on purpose, and which one turns "the stop is in" from a full answer into a partial one.Page 17
- 18The single modeled comparison, sitting in this report's own one-page summary, between the two groups' worst-case outcome.Page 18
- 19Six named studies spanning 1956 to 2015, and which one has nothing to do with psychology at all.Page 19
- 20The exact reason this report's two case studies aren't tied to a genuine, identifiable trader, disclosed on the same page as every other limit this report holds itself to.Page 20
Read this once and the next date on your calendar stops being an afterthought. You'll have the modeled cost of leaving it unresized, and the four-step sequence for sizing it on purpose instead.
HABITS
★
Certificate of Guarantee
60-Day, No-Questions-Asked
If The Catalyst Trade doesn't earn its place on your desk, email us any time within 60 days of purchase for a full refund. No form to fill out. No reason required.
Backed personally by Jason Parker, founder of Trading Habits. He built this himself, covered by the same guarantee above.
Instant Download
$7One-time payment. No subscription.
Order Now20-PAGE PDF · DELIVERED IMMEDIATELY AFTER CHECKOUT · 60-DAY GUARANTEE
Behind The Report
Why A Known Date Still Gets Sized Like An Ordinary One
The Concept
A scheduled catalyst, an earnings release, a Federal Reserve decision, a CPI report, is public knowledge well before it happens. Options pricing already reflects it: the priced-in "expected move" on a stock ahead of earnings is routinely two to four times an ordinary day's range for the same name. A stop distance built from an ordinary day's chop ignores information the market has already made public.
The catalyst trade is what happens when that stop distance, or that position size, gets carried through the date unchanged. The order is genuine. It simply was not built for the day it is about to face.
Where It Comes From
Amos Tversky and Daniel Kahneman named the availability heuristic in a 1973 paper in Cognitive Psychology: people judge how likely or how large an event is by how easily examples come to mind, not by its actual base rate. Ordinary trading days vastly outnumber scheduled-catalyst days, so recent memory keeps supplying an ordinary day's range as the default.
Neil Weinstein documented a second mechanism in a 1980 paper in the Journal of Personality and Social Psychology: people rate their own odds of a bad outcome as lower than the odds they'd assign someone else in an identical position. Together, the two mechanisms explain why a date that is fully known in advance still gets priced like any other session.
The Options Market's Own Estimate Of The Day
Illustrative, matching the pattern widely reported by options-education desks that publish a stock's priced-in "expected move," not a live measurement of any specific ticker. The report's own Figure 1 walks this comparison directly, and Figure 2 shows the shape options pricing assigns to the days around the date.
Try It: Move The Calendar, Watch The Priced-In Range Jump
Nothing about the stop distance changes when you move the slider. Only the kind of day it's about to face does. That's the entire mechanism this report is about: the identical stop distance is a reasonable bet on one kind of day, and a stop calibrated to the wrong distribution entirely on the other.
Background only. The report itself models the dollar cost of holding an unresized position through a scheduled release across two worked case studies and a 3,000-account simulation, not only the mechanism behind why it happens.
Common Questions
What counts as a "scheduled catalyst" in this report?
Any date-and-time event known publicly in advance: a company's earnings release, a Federal Reserve rate decision, or a government report such as CPI or the monthly jobs report. The report is specifically about dates that are already on the calendar, not surprise headlines.
Where does the "expected move" figure actually come from?
It's derived from standard options math: an at-the-money straddle's price, divided by the stock price, gives the market's own estimate of how far the stock is priced to move by the next session. Many broker and options platforms publish this figure directly before earnings.
Is this report telling me to avoid trading through earnings or FOMC?
No. It's about whether the size, stop, or hedge carried through the date matches what the trader actually intends to risk, given what the market has already priced in, rather than an ordinary day's stop distance left untouched because resizing never became its own decision.
Does the slider tool above save anything I enter?
No. It runs entirely in your browser and resets on refresh. Nothing is saved, logged, or sent anywhere.
Sources & Further Reading
-
Patell, J. M. & Wolfson, M. A. (1979). “Anticipated Information Releases Reflected in Call Option Prices.” Journal of Accounting and Economics, 1(2), 117-140.
Documented that options markets price a measurable rise in expected volatility ahead of a scheduled earnings announcement.
-
Tversky, A. & Kahneman, D. (1973). “Availability: A Heuristic for Judging Frequency and Probability.” Cognitive Psychology, 5(2), 207-232.
Source of the availability mechanism: rare, larger events get underweighted relative to the far more numerous ordinary days that populate recent memory.
-
Weinstein, N. D. (1980). “Unrealistic Optimism About Future Life Events.” Journal of Personality and Social Psychology, 39(5), 806-820.
Source of the optimism-bias mechanism: people rate their own odds of a bad outcome as lower than the odds they'd assign someone else in an identical position.