A Stock Closes At $84. The Report Drops After The Bell. By Morning It's At $92 Or $76, And Nothing You Do In The Moment Changes Which One.
There's no chart to watch and no stop that could have fired.
What's left is a closed position, a scheduled report, and roughly seventeen hours between the close and the next bell.
You'll learn to size a position for its actual worst case instead of a stop-loss distance that doesn't exist overnight, and to price an option against a move the stock actually has a chance of delivering.
You'll get IV crush, the gap, drift versus reversal, four setups, straddle and spread strategy, and binary-event sizing, six ideas that sound simple individually and completely change how an earnings report reads once they're understood together.
You'll work through 15 interactive candlestick drills built around post-earnings continuation and reversal, calling Buy or Sell before the next candle prints, then seeing what actually happened.
You'll get the five behavioral patterns that blow up earnings accounts, named plainly, and an 8-week path from paper to live size.
There's no chart to watch and no stop that could have fired.Jason Parker, Founder of Trading Habits
Introducing The Earnings Trading System: 12 modules, no ticker calendar, no beat-or-miss predictions, no chat room. The mechanics behind sizing and structuring a position around an event you can't watch unfold live.
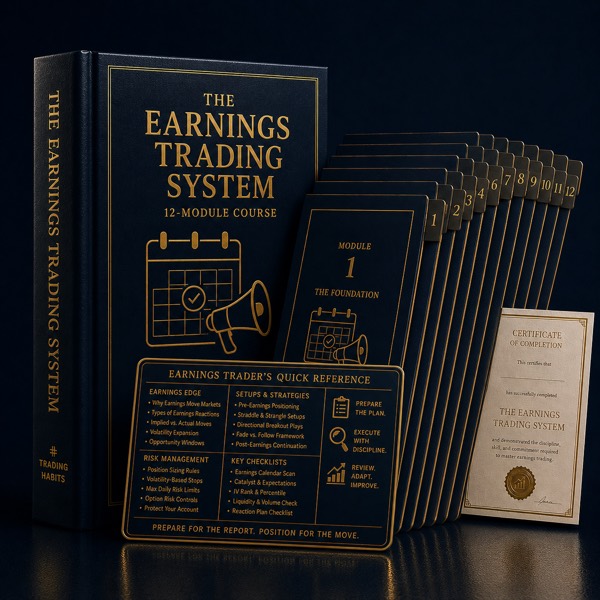
A Trading Habits Course
The Earnings Trading System
IV crush, the gap, drift versus reversal, four setups, options strategy, and binary-event position sizing, read the way a genuine earnings trader reads them.
- Length 12 modules, built for genuine depth, not padding
- Format A private, self-paced course page with working calculators and a candlestick drill built into the lessons, not links out to them
- Access Instant, right after checkout, yours to re-read for good
- Covers Reading a report, IV crush, the gap, post-earnings drift, post-earnings reversal, four setups, straddle and spread strategy, binary-event sizing, a personal calendar, and the behavioral guardrails that keep an account alive
- Author TradingHabits.com
Built for one job: sizing and structuring a position around a scheduled event that can't be watched, and can't be stopped out, while it happens.

Try It First
One Post-Earnings Candle, Scored Live
Try it first: this is one drill from the full Setup Practice Lab that ships with the course. Watch a post-earnings candle build live and call buy or sell before it closes, the same read you'd need to make in the minutes after a print instead of after the chart already tells the story.
What's Inside
The 12 Modules
- 01What earnings trading actually is: confirmed vs. estimated dates, and why BMO and AMC reactions behave completely differently. You stop scheduling trades off a guessed date and stop being surprised by a report you should have seen coming.Module 1
- 02Reading the report like a trader: the headline beat or miss, why guidance usually moves the stock more, and the whisper number. You read the same release everyone else has open and see the number that's actually going to move the stock.Module 2
- 03IV crush: reading the market's own expected move off the straddle price, and what crush does to that position the instant the report is out. You stop buying options priced for a move the stock was never going to deliver.Module 3
- 04The gap: measuring it against the same relative-volume framework that governs any other gap in this shop's catalog. You get one consistent way to size up a gap instead of eyeballing it fresh every single report.Module 4
- 05Post-earnings announcement drift: the 1968 academic finding, and why it still shows up in reports today. You get a documented reason to hold a working position past the open instead of closing it out of habit.Module 5
- 06Post-earnings reversal: fade the pop, fade the drop, and why neither drift nor reversal is the default outcome. You stop assuming every gap keeps going and start checking which pattern is actually in front of you.Module 6
- 07Four setups worth studying and backtesting personally, each one built from the mechanics already covered. You get a concrete starting point to test on your own names instead of building a system from scratch.Module 7
- 08Options strategy around earnings: long straddles, defined-risk spreads, and why premium sellers have structure on their side, and their own risk. You pick a structure that matches what you actually believe about the move, instead of defaulting to whatever's familiar.Module 8
- 09Position sizing for a binary, gap-risk event: why there's no stop, and how to size by worst case instead. You walk into every earnings report already knowing the worst dollar number possible, before it happens, not after.Module 9
- 10Building a personal earnings calendar and a pre-trade checklist that gets checked before every position. You catch the sloppy entry before you place it instead of explaining it away after the fill.Module 10
- 11The five behavioral patterns that blow up earnings accounts, named plainly. You recognize your own next mistake while it's still a pattern on a page, not a loss in your account.Module 11
- 12An 8-week path from paper to live size. You get an actual sequence to follow instead of guessing when you're ready to trade this live.Module 12
+ Setup Practice Lab in Module 7: 15 interactive candlestick drills built around post-earnings continuation and reversal. Watch a chart build, call Buy or Sell before the next candle prints, then see what happened.
Knowing what a post-earnings gap usually does is not the same skill as calling it correctly before the fill happens. That's the gap this drill is built to close.
+ Bonus Module: Gap-to-ATR, reading a gap against the stock's own average true range instead of a flat percentage, so a 6% move reads correctly whether it's a sleepy utility or a biotech that swings 5% on an ordinary Tuesday.
HABITS
★
Certificate of Guarantee
60-Day, No-Questions-Asked
If The Earnings Trading System doesn't earn its place in your process, email us any time within 60 days of purchase for a full refund. No form to fill out. No reason required.
Instant Access
$299One-time payment. No subscription.
Get Instant Access12-MODULE DIGITAL COURSE · DELIVERED IMMEDIATELY AFTER CHECKOUT · 60-DAY GUARANTEE
Behind The Course
Where Post-Earnings Drift Was Actually Discovered
A 1968 Finding That Broke a Core Assumption
Ray Ball and Philip Brown published "An Empirical Evaluation of Accounting Income Numbers" in the Journal of Accounting Research in 1968. Studying how stock prices reacted to earnings announcements, they found something the dominant efficient-market thinking of the time didn't predict: prices kept drifting in the direction of an earnings surprise for months afterward, instead of adjusting immediately and completely the moment the news came out.
Why It Still Matters to a Trader Today
The finding has been replicated across decades of subsequent academic research and remains one of the most well-documented anomalies in finance, even as its size has generally shrunk in the decades since as markets have gotten faster. Module 5 covers the actual shape of that drift and why it sits alongside an equally valid, opposite tendency: some earnings gaps reverse instead of continuing, covered in Module 6.
From a 1968 Paper to a Documented Market Anomaly
A finding from 1968 that directly challenged the strict efficient-market thinking of its era, replicated for decades since, still visible in how earnings reactions unfold today.
Try It: Step Through The Research Timeline
Same three milestones as the timeline above. Drag through them in order and a single 1968 paper stops reading as a historical curiosity and starts reading as the origin of a pattern this course's Module 5 still teaches today.
Background only. The course itself works the expected-move, gap, sizing, and payoff math an earnings account runs on.
Common Questions
Who discovered post-earnings announcement drift?
Ray Ball and Philip Brown, in a 1968 paper in the Journal of Accounting Research. They found that stock prices kept drifting in the direction of an earnings surprise for months after the announcement, instead of adjusting all at once.
Does that mean every earnings gap keeps drifting in the same direction?
No. Module 6 covers the equally valid, opposite pattern: many earnings gaps reverse instead of continuing. Both outcomes are documented and common. Neither is the guaranteed default for any individual stock.
Why can't a stop-loss protect an earnings position the way it protects a normal trade?
Because the market is closed, or trading on thin after-hours volume, while the report comes out and the gap happens. There's no order that can execute at a chosen price once the move has already occurred overnight. Module 9 covers sizing by worst case instead.
Sources & Further Reading
-
Ball, R. & Brown, P. (1968). “An Empirical Evaluation of Accounting Income Numbers.” Journal of Accounting Research, 6(2), 159-178.
The original post-earnings-announcement drift finding Module 5 is built on.