A Trading Habits Course
Read The Stock That's Already Moved 20% Before You Finish Your Coffee
Every morning, a handful of stocks move 10, 20, 40 percent before most traders finish their coffee.
Somebody caught it.
What almost never gets shown is the pile of traders who bought the exact same stock two hours later, after the volume that actually mattered had already come and gone.
You'll get ten modules on relative volume, premarket gaps, new highs, momentum scanners, the opening range, and VWAP, the six ideas that sound simple individually and completely change how a chart reads once you understand them together.
You'll get the calculators and scanner criteria built directly into the lessons instead of links out to some other tool.
You'll get the ATR-based sizing math for a fast-moving stock and the five behavioral patterns that blow up momentum accounts, named plainly instead of softened.
Ten modules.
No signals, no ticker lists, no chat room.
You get the mechanics behind reading a fast-moving stock before it's already too late to act on it.
Every morning, a handful of stocks move 10, 20, 40 percent before most traders finish their coffee.Jason Parker, Founder of Trading Habits
Introducing The Momentum Trading System.
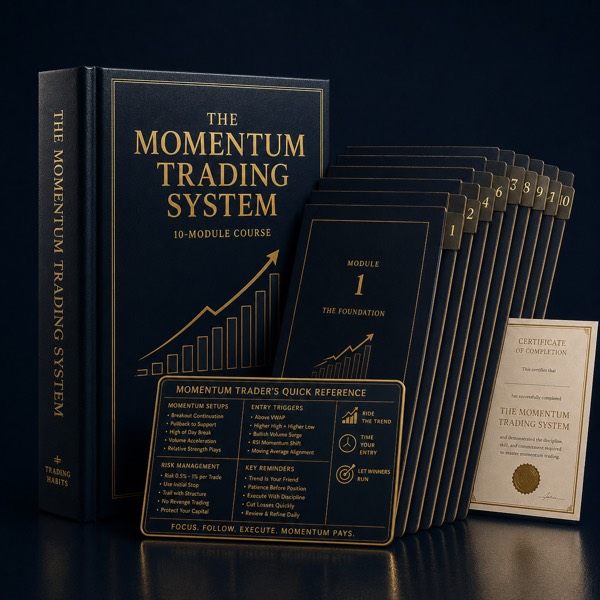
The Momentum Trading System
Relative volume, premarket gappers, new highs, momentum scanners, VWAP breaks, and opening range breakouts, read the way a genuine momentum trader reads them.
- Length 10 modules, built for genuine depth, not padding
- Format A private, self-paced course page with working calculators and a scanner builder built into the lessons, not links out to them
- Access Instant, right after checkout, yours to re-read for good
- Covers Relative volume, premarket gaps, new highs, scanner criteria, the opening range and ORB, VWAP, four setup archetypes, ATR-based sizing, and the behavioral guardrails that keep an account alive
- Author TradingHabits.com
Built for one job: knowing whether a fast-moving stock is a genuine setup or a move that already happened, before risking money on the difference.

Try It First
One Momentum Candle, Called Before It Closes
Try it first: this is one drill from the Setup Practice Lab that ships with the course. A momentum candle builds in real time and you call buy or sell before it closes, the same split-second read a live scanner alert actually demands.
What's Inside
The 10 Modules
- 01What momentum trading is: the holding-period spectrum, and why every move has to be read relative to something. You stop treating "momentum" as a vibe and start treating it as a measurement.Module 1
- 02Relative volume: the fuel behind every genuine move, and the calculator that tells quiet from genuinely active. You stop chasing a stock just because it's moving and start confirming real participation is behind it.Module 2
- 03Premarket gappers: gap-and-go versus gap-and-fade, and the liquidity trap hiding behind a displayed gap percentage. You stop getting fooled by a big premarket number that quietly fades once real volume shows up.Module 3
- 04Stocks making new highs: why the absence of trapped sellers changes how a breakout behaves. You learn why some breakouts run clean and others stall immediately, before you're in the trade.Module 4
- 05Momentum scanners: building a watchlist that finds you, and why more filters isn't automatically better. You stop manually scrolling tickers and start letting your own criteria surface the setup.Module 5
- 06The opening range and opening range breakouts: the speed-versus-confirmation trade-off, straight from the source that popularized it. You get a rule for how much confirmation is enough instead of guessing under pressure at 9:31.Module 6
- 07VWAP breaks: the actual institutional execution benchmark, reclaim and reject patterns, and the history behind it. You start trading the same level the desks on the other side of your fill are trading against.Module 7
- 08Four momentum setups worth studying and backtesting personally, each one built from the tools already covered. You get a starting point to test against your own data instead of a black-box rule to trust blind.Module 8
- 09Position sizing for wide-range momentum names: why a flat share count fails a fast-moving stock. You stop taking the same size on a calm stock and a wild one, and start sizing to the actual risk in front of you.Module 9
- 10The five behavioral patterns that blow up momentum accounts, and an 8-week path from paper to live size. You get a way to recognize your own worst habit before it costs you the account, not after.Module 10
+ Setup Practice Lab in Module 8: 15 interactive candlestick drills. Watch a chart build, call Buy or Sell before the next candle prints, then see what happened.
Spotting a trend is easy on a chart that already closed. Catching the continuation while it's still deciding is the part this system actually drills.
HABITS
★
Certificate of Guarantee
60-Day, No-Questions-Asked
If The Momentum Trading System doesn't earn its place in your process, email us any time within 60 days of purchase for a full refund. No form to fill out. No reason required.
Backed personally by Jason Parker, founder of Trading Habits. He built this himself, covered by the same guarantee above.
Instant Access
$299One-time payment. No subscription.
Get Instant Access10-MODULE DIGITAL COURSE · DELIVERED IMMEDIATELY AFTER CHECKOUT · 60-DAY GUARANTEE
Behind The Course
Where the Opening Range and VWAP Came From
The Opening Range Breakout
Trader Toby Crabel formally documented and popularized the opening range breakout in his 1990 book Day Trading with Short Term Price Patterns and Opening Range Breakout, published by Traders Press. The book ran statistical analysis across the relationship between a session's open, high, low, and close to identify which early-session patterns carried predictive weight, rather than relying on a trader's gut feel about the first few minutes.
VWAP's Institutional Origin
The first documented VWAP-benchmarked trade is generally credited to James Elkins, then head trader at the agency brokerage Abel Noser, who used it in 1984 to execute a Ford Motor Company pension fund order. The concept was formalized academically four years later in a 1988 Journal of Finance paper by Berkowitz, Logue, and Noser, which used VWAP to measure the total cost of transactions on the New York Stock Exchange.
Module 7 covers exactly why that institutional lineage still matters intraday: VWAP is the actual benchmark large desks are trading against all session long, not a retail-only indicator that happened to catch on.
From a 1984 Block Trade to a 1990 Trading Book
VWAP's first documented benchmarked trade came in 1984, formalized academically in 1988. Toby Crabel's opening range breakout research followed in 1990, the same decade both ideas moved from institutional desks into the tools this course teaches.
Try It: Step Through The Three Milestones
Same three milestones as the timeline above. Drag through them in order and the six years between the first VWAP-benchmarked trade and Crabel's opening range breakout book stop being three isolated dates and start reading as one continuous decade.
Background only. The course itself works the relative volume, gap, VWAP, and sizing math a momentum account runs on.
Common Questions
Who actually documented the opening range breakout as a genuine pattern?
Trader Toby Crabel, in his 1990 book Day Trading with Short Term Price Patterns and Opening Range Breakout. He ran statistical analysis across a session's open, high, low, and close instead of relying on gut feel about the first few minutes.
Where did VWAP actually come from?
An institutional trading desk, not a retail indicator. James Elkins, head trader at agency brokerage Abel Noser, used it in 1984 to execute a Ford Motor Company pension fund order. It was formalized academically four years later in a 1988 Journal of Finance paper.
Why does VWAP still matter intraday if it started as an institutional cost-measurement tool?
Because it's still the actual benchmark large desks trade against all session long, not a retail-only indicator that happened to catch on. That institutional lineage is exactly what Module 7 covers.
Sources & Further Reading
-
Crabel, T. (1990). Day Trading with Short Term Price Patterns and Opening Range Breakout. Traders Press.
Formally documented and popularized the opening range breakout, the subject of Module 6.
-
Berkowitz, S., Logue, D. & Noser, E. (1988). Published in The Journal of Finance.
Formalized VWAP academically, four years after its first documented benchmarked use in a 1984 Ford Motor Company pension fund order.